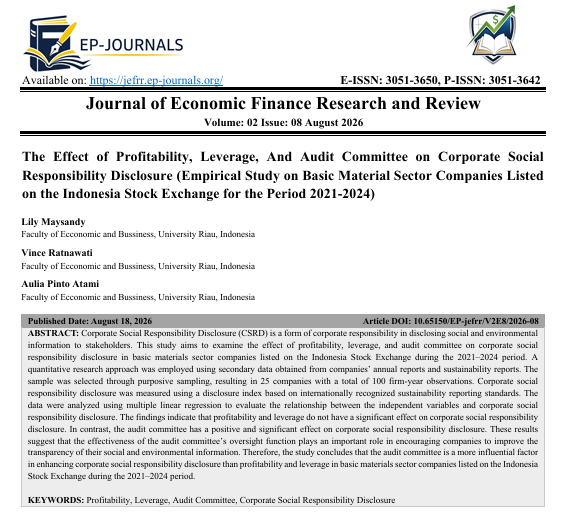
The Effect of Profitability, Leverage, And Audit Committee on Corporate Social Responsibility Disclosure (Empirical Study on Basic Material Sector Companies Listed on the Indonesia Stock Exchange for the Period 2021-2024)
DOI:
https://doi.org/10.65150/EP-jefrr/V2E8/2026-08Keywords:
Profitability, Leverage, Audit Committee, Corporate Social Responsibility DisclosureAbstract
Corporate Social Responsibility Disclosure (CSRD) is a form of corporate responsibility in disclosing social and environmental information to stakeholders. This study aims to examine the effect of profitability, leverage, and audit committee on corporate social responsibility disclosure in basic materials sector companies listed on the Indonesia Stock Exchange during the 2021–2024 period. A quantitative research approach was employed using secondary data obtained from companies’ annual reports and sustainability reports. The sample was selected through purposive sampling, resulting in 25 companies with a total of 100 firm-year observations. Corporate social responsibility disclosure was measured using a disclosure index based on internationally recognized sustainability reporting standards. The data were analyzed using multiple linear regression to evaluate the relationship between the independent variables and corporate social responsibility disclosure. The findings indicate that profitability and leverage do not have a significant effect on corporate social responsibility disclosure. In contrast, the audit committee has a positive and significant effect on corporate social responsibility disclosure. These results suggest that the effectiveness of the audit committee’s oversight function plays an important role in encouraging companies to improve the transparency of their social and environmental information. Therefore, the study concludes that the audit committee is a more influential factor in enhancing corporate social responsibility disclosure than profitability and leverage in basic materials sector companies listed on the Indonesia Stock Exchange during the 2021–2024 period.
References
1) Abidin, J., & Lestari, S. A. (2020). The Pengaruh Ukuran perusahaan dan Ukuran Komite Audit terhadap Pengungkapan Corporate Social Responsibility. Owner, 4(1), 48. https://doi.org/10.33395/owner.v4i1.214
2) Agistiani, Alfina., Nurfauziah, F. L., & Latifah, Euis. (2023). The Effect of Managerial Ownership, Company Size, and Audit Committee on CSR Disclosure. Governors, 2(1), 09–18. https://doi.org/10.47709/governors.v2il.1979
3) Agnes, Katarina. (2023). The Effect of Green Accounting, Company Size, Profitability, Media Disclosure, and Board of Commissioners’ Size on Corporate Social Responsibility Disclosure. International Journal Papier, 4(2), 001–017. https://doi.org/10.47667/ijppr.v4il.203
4) Ahadi, G. D., Nur, N., & Ersela, L. (2023). The Simulation Study of Normality Test Using Kolmogorov-Smirnov,. 6(1).
5) Aisy, N., & Rahmah, N. (2024). Pengaruh Leverage dan Profitabilitas Terhadap PengungkapanCorporate Social Responsibility. Journal Of Social Science Research, 4(3), 5519–5530.
6) Asrorudin, A., Ismanto, J., Akuntansi, P. S., Ekonomi, F., & Pamulang, U. (2023). 1 1,2,3. 4(1), 446–452.
7) Handayani, P., & Maharani, N. K. (2021). Effect of Environmental Performance, Company Size, and Profitability on Corporate Social Responsibility Disclosures. PAPATUNG: Jurnal Ilmu Administrasi Publik, Pemerintahan Dan Politik, 4(1), 121–133.
https://doi.org/10.54783/japp.v4i1.446
8) Herizona, B. S., & Yuliana, I. (2021). Pengaruh Ukuran Dewan Komisaris, Independensi Dewan Komisaris, dan Komite Audit terhadap Corporate Social Responsibility Disclosure dengan Profitabilitas sebagai Variabel Moderasi. Jurnal Manajemen Dan Keuangan, 10(1), 108–128. https://doi.org/10.33059/jmk.v10i1.2935
9) Isnabella, H., & Trisnawati, R. (2022). Pengaruh Profitabilitas, Leverage, Enterprise Size, Dan Komite Audit Terhadap Pengungkapan Corporate Social Responsibility (Studi Empiris Pada Perusahaan Manufaktur Yang Terdaftar Di Bursa Efek Indonesia Periode 20182021). Jurnal Ekonomi Dan Bisnis, 11(1), 446–453.
10) Isra Laili, N., & Apramilda, R. (2023). ANALISIS PENGARUH UKURAN PERUSAHAAN, LEVERAGE, DAN PROFITABILITAS TERHADAP PENGUNGKAPAN CORPORATE SOCIAL RESPONSIBILITY (Studi Kasus Pada Perusahaan Pertambangan Yang Terdaftar di Bursa Efek Indonesia Pada Tahun 2015-2019). Reliable Accounting Journal, 2(2), 27–38. https://doi.org/10.36352/raj.v2i2.526
11) KLHK Setop Operasional 11 Pabrik Pemicu Pencemaran Udara di Jabodetabek. Diakses dari https://news.detik.com/berita/d-
7501552/klhk-setop-operasional-11-pabrik-pemicu-pencemaran-udara-dijabodetabek#:~:text=Kementerian%20Lingkungan%20Hidup%20dan%20Kehutanan,51%20perusahaan%20atau%20perizinan%20ber usaha.
12) Kurniawa, K. A., & Yuniarta, G. A. (2020). Pengaruh Profitabilitas, Ukuran Perusahaan, Likuiditas, dan Risk Minimization terhadap Pengungkapan Corporate Social Responsibility. Jurnal Akuntansi Profesi, 11(1), 2338-6177.
13) Lestari, S. A., & Jaenal, A. (2020). Pengaruh Ukuran Perusahaan dan Ukuran Komite Audit terhadap Pengungkapan Corporate Social Responsibility. Owner, 4(1), 2548-9224. https://doi.org/10.33395/owner.v4il.194
14) Lie, C. A., & Setyani, A. Y. (2023). Pengaruh Profitabilitas dan Gender Diversity terhadap Luas Pengungkapan CSR (Corporate Social Responsibility). Prosiding Seminar Nasional Forum Manajemen Indonesia - e-ISSN 3026-4499, 1, 243–256.
https://doi.org/10.47747/snfmi.v1i.1505
15) Maharani, P. R., & Pertiwi, T. K. (2022). Pengaruh Profitabilitas, Leverage, Dan Ukuran Perusahaan Terhadap Pengungkapan Corporate Social Responsibility. At-Tadbir : Jurnal Ilmiah Manajemen, 6(1), 41. https://doi.org/10.31602/atd.v6i1.5873
16) Malisa, Y., Gultom, S. A., & Sibarani, J. L. (2022). Pengaruh Profitabilitas, Ukuran Perusahaan, dan Ukuran KAP terhadap Pengungkapan Corporate Social Responsibility (CSR). Jurnal Akuntansi, Keuangan Dan Perpajakan, 5(2), 114–127. https://doi.org/10.51510/jakp.v5i2.985.
17) Peraturan Otoritas Jasa Keuangan Nomor 40 Tahun 2007, https://www.ojk.go.id/sustainable-finance/id/peraturan/undangundang/Documents/5.%20UU-40-2007%20PERSEROAN%20TERBATAS.pdf
18) Peraturan Pemerintah Nomor 47 tahun 2012, https://peraturan.bpk.go.id/Home/Details/5260/pp-no-47-tahun-2012
19) Rachman Haikal, F., & Rosdiana, Y. (2023). Pengaruh Kinerja Lingkungan Dan Profitabilitas Terhadap Pengungkapan Corporate Social Responsibility Disclosure CSRD. … and Digital Business …, 4(1), 476–484.
20) Rivandi, M., & Putra, R. J. (2021). Pengaruh Ukuran Perusahaan, Profitabilitas dan Komite Audit Terhadap Pengungkapan Corporate Social Responsibility. Owner, 5(2), 513–524. https://doi.org/10.33395/owner.v5i2.468
21) Royhan, & Yuniati, T. (2021). Pengaruh Current Ratio ,Net Profit Margin Dan Return On Equity Terhadap Harga Saham Pada Perusahaan Otomotif Dan Tri Yuniati Sekolah Tinggi Ilmu Ekonomi Indonesia (STIESIA) Surabaya Royhan Pendahuluan Pertumbuhan kinerja keuangan industry otomotif dan. 1-16.
22) Sari, P. A., & Handini, B. T. (2021). Pengaruh Kepemilikan Manajerial, Institusional Dan Komite Audit Terhadap Pengungkapan Corporate Social Responsibility. El Muhasaba Jurnal Akuntansi, 12(2), 102–115. https://doi.org/10.18860/em.v12i2.10882
23) Sugiharto, B., Umiyati, I., & Nuraini, W. (2023). The Effect Of Profitability, Leverage, Institutional Ownership Company Size And Gender Diversity Of The Board Of Commissioners On Corporate Social Responsibility (CSR) Disclosure. Accounting Research Journal Of Sutaatmadja, 07(1), 52–71.
24) Sugiharto, Bambang., Umiyati, Indah., Nuraini, Winda. (2023). The Effect of Profitability, Leverage, Institusional Ownership Company Size and Corporate Social Responsibility (CSR) Disclosure. Accounting Research Journal of Sutaatmadja (ACCRUAS), 7(1), 52–71. https://doi.org/10.35310/accruals.v7i01.1018
25) Sugiyono. (2020). Metode penelitian kuantitatif dan kualitatif dan R&D. Alfabeta
26) Solimun, A. A. R. Fernandes, & Nurjannah. (2017). Metode Statistika Multivariat. Pemodelan Persamaan Struktural (SEM) Pendekatan WarpPLS. UB Press. 27) Yanti, N. L. E. K., Endiana, I. D. M., & Pramesti, I. G. A. A. (2021). Pengaruh Ukuran Perusahan, Ukuran Dewan Komisaris, Kepemilikan Institusional, Leverage, Dan Profitabilitas terhadap Pengungkapan Corporate Social Responsibility. Ekonomi Bisnis, 3(1), 43–51. https://e-journal.unmas.ac.id/index.php/kharisma/article/view/1676
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Lily Maysandy , Vince Ratnawati , Aulia Pinto Atami (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.