Uncovering the Latent Structure of Liquidity Risk Using Machine Learning Clustering Algorithms: Evidence from Vietnamese Commercial Banks
DOI:
https://doi.org/10.65150/EP-jefrr/V2E3/2026-02Keywords:
Commercial banks, Clustering, Hierarchical clustering, K-means, Liquidity risk.Abstract
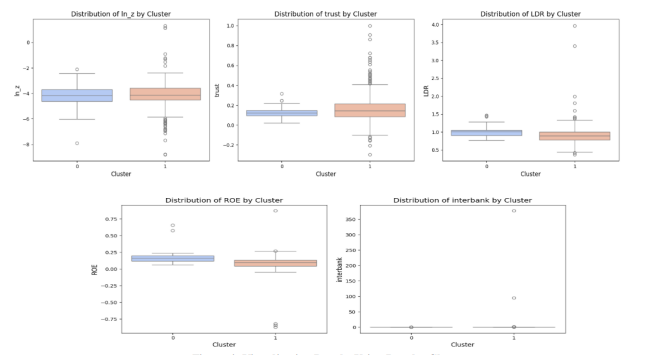
This study explores the latent structure of liquidity risk in the Vietnamese commercial banking system through the application of unsupervised machine learning clustering algorithms. Using panel data collected from the financial statements of 31 Vietnamese commercial banks over the period 2009–2024, the study constructs a set of indicators capturing banks’ liquidity characteristics, profitability, and funding structure. Representative clustering techniques, including K-means clustering and Hierarchical clustering, are employed to identify groups of banks exhibiting similar levels of liquidity risk. The empirical findings reveal a relatively clear segmentation within the banking system in terms of liquidity stability, associated with differences in operational scale, business performance, and reliance on short-term funding sources. The applied clustering algorithms effectively highlight the underlying structures embedded in the data, thereby reflecting the heterogeneity of liquidity risk across the system. This study contributes to the growing literature by incorporating a machine learning–based approach into liquidity risk analysis and provides empirical evidence to support supervisory practices and prudential risk management in the banking sector.
References
1) Basel Committee on Banking Supervision. (2008). Principles for Sound Liquidity Risk Management and Supervision. Bank for International Settlements.
2) Beatty, Anne L. and Liao, Scott and Zhang, Haiwen (2018). The Effect of Banks’ Financial Reporting on Syndicated Loan Structures. Journal of Accounting & Economics (JAE), http://dx.doi.org/10.2139/ssrn.3256916
3) Bui Dan Thanh, Nghiem Hoang Thao Vy, & Nguyen Ngoc Huyen. (2022). Factors affecting liquidity risk of commercial banks in Vietnam. Asian Journal of Economics and Banking. https://doi.org/10.63065/ajeb.vn.2022.198.81408
4) Cihak, M., Hesse, H (2010). Islamic Banks and Financial Stability: An Empirical Analysis. J Financ Serv Res 38, 95–113.https://doi.org/10.1007/s10693-010-0089-0
5) Dietrich, A., & Wanzenried, G. (2011). Determinants of bank profitability before and during the crisis: Evidence from Switzerland. Journal of International Financial Markets, Institutions and Money. https://doi.org/10.1016/j.intfin.2010.11.002
6) Duttweiler, R. (2009). Managing Liquidity in Banks: A Top Down Approach. John Wiley & Sons Ltd. DOI:10.1002/9781119206415
7) Duttweiler, R. (2016). Liquidity Risk Management: A Practitioner's Perspective. John Wiley & Sons.https://lascoco.lagosstate.gov.ng/package/liquidity-risk-management_-a-practitioners-perspective-pdfdrive-pdf/
8) Hannan, T. H., & Hanweck, G. A. (1988). Bank insolvency risk and the market for large certificates of deposit. Journal of Money, Credit and Banking. Vol 20(2), pp.203-211. https://doi.org/10.2307/1992111
9) Lepetit, L., & Strobel, F. (2013). Bank insolvency risk and time-varying Z-score measures. Journal of International Financial Markets, Institutions and Money. Vol 25, pp.73-87. https://doi.org/10.1016/j.intfin.2013.01.004
10) Milojevi´ C, N., & Redzepagic, S. (2021). Prospects of artificial intelligence and machine learning application in banking risk management. Journal of Central Banking Theory and Practice, 10(3), 41–57. https://doi.org/10.2478/jcbtp-2021-0023 .
11) Myra, V. De L. (2020). The impact of credit risk and macroeconomic factors on profitability: the case of the ASEAN banks. Banks and Bank Systems, 15(1), 21-29. http://dx.doi.org/10.21511/bbs.15(1).2020.03
12) Nguyen Duc Trung & Tran Trong Huy. (2024). Determinants of Vietnam commercial banks liquidity risk. Banking Review. https://tapchinganhang.gov.vn/cac-nhan-to-tac-dong-den-rui-ro-thanh-khoan-cua-cac-ngan-hang-thuong-mai-viet-nam-12199.html
13) Nguyen Van Tien. (2010). Risk Management in Banking Business. Statistics Publishing House.
14) Peter J. Rousseeuw (1987). Silhouettes: A graphical aid to the interpretation and validation of cluster analysis. Journal of Computational and Applied Mathematics, 20, p53-65. https://doi.org/10.1016/0377-0427(87)90125-7
15) Truong Quang Thong & Pham Minh Tien. (2014). Factors affecting liquidity risk: The case of Vietnamese joint-stock commercial banks. Issue 21, Financial and Monetary Market Review
16) Truong Thi Thuy Duong & Le Hai Trung. (2023). Application of machine learning in identifying corporate financial distress. Journal of Economics and Development. DOI: https://doi.org/10.33301/JED.VI.1066
17) Valentin Lennart Heß, Bruno Damásio (2025). Machine learning in banking risk management: Mapping a decade of evolution, International Journal of Information Management Data Insights, Volume 5, Issue 1, https://doi.org/10.1016/j.jjimei.2025.100324
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Tran Thi Thuy Huyen, Hoang Thao Nhi, Pham Ngoc Khue, Nguyen Thi Lan Huong, Nguyen Thu Ha, Vu Thi Thu Huong (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.