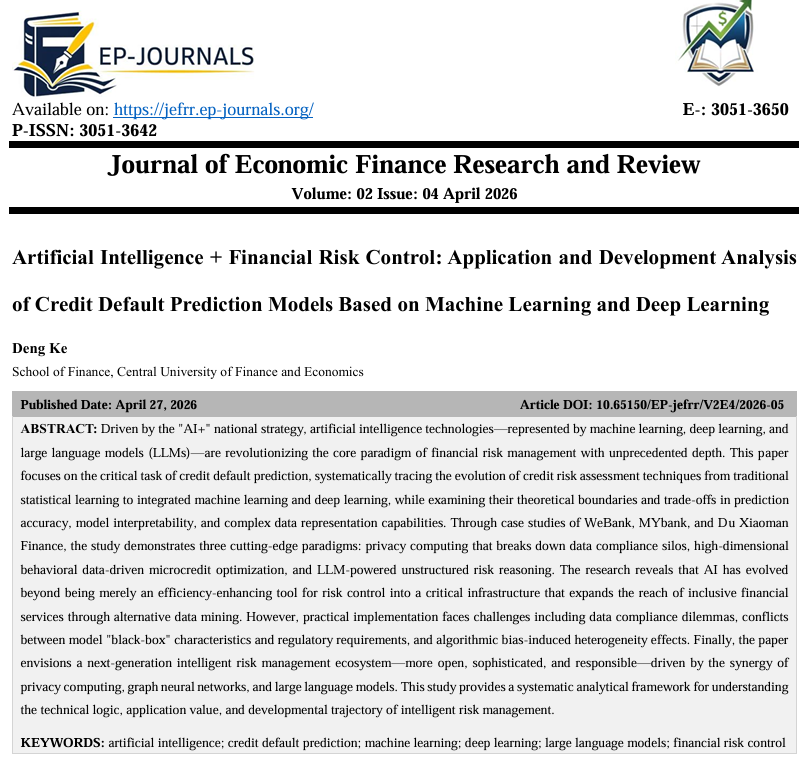
Artificial Intelligence + Financial Risk Control: Application and Development Analysis of Credit Default Prediction Models Based on Machine Learning and Deep Learning
DOI:
https://doi.org/10.65150/EP-jefrr/V2E4/2026-06Keywords:
artificial intelligence; credit default prediction; machine learning; deep learning; large language models; financial risk controlAbstract
Driven by the "AI+" national strategy, artificial intelligence technologies—represented by machine learning, deep learning, and large language models (LLMs)—are revolutionizing the core paradigm of financial risk management with unprecedented depth. This paper focuses on the critical task of credit default prediction, systematically tracing the evolution of credit risk assessment techniques from traditional statistical learning to integrated machine learning and deep learning, while examining their theoretical boundaries and trade-offs in prediction accuracy, model interpretability, and complex data representation capabilities. Through case studies of WeBank, MYbank, and Du Xiaoman Finance, the study demonstrates three cutting-edge paradigms: privacy computing that breaks down data compliance silos, high-dimensional behavioral data-driven microcredit optimization, and LLM-powered unstructured risk reasoning. The research reveals that AI has evolved beyond being merely an efficiency-enhancing tool for risk control into a critical infrastructure that expands the reach of inclusive financial services through alternative data mining. However, practical implementation faces challenges including data compliance dilemmas, conflicts between model "black-box" characteristics and regulatory requirements, and algorithmic bias-induced heterogeneity effects. Finally, the paper envisions a next-generation intelligent risk management ecosystem—more open, sophisticated, and responsible—driven by the synergy of privacy computing, graph neural networks, and large language models. This study provides a systematic analytical framework for understanding the technical logic, application value, and developmental trajectory of intelligent risk management.
References
1) Chen Wei, Zhou Quanshi, Chen Zhensong, et al. Research on Green Credit Default Risk Prediction for Listed Companies Based on Hybrid Deep Learning Models [J]. Management Review, 2025,37(09):27-41.
2) Li Yinqian. Research on Credit Default Prediction Based on the LightGBM Model and Multimodal Data [J]. Financial Customer, 2025, (11):14-16.
3) She Kaiwen, Shen Yu, Zhao Shaoyang. The Impact of Big Data on Bank Credit Behavior: Evidence from the Digital Social Credit Platform [J]. Economic Research, 2024,59(03):147–165.
4) Yang Pengbo, Zhang Chenghu, Zhang Xiang. Research on a Credit Default Probability Prediction Model for Listed Companies Based on Logistic Regression Analysis [J]. Economic Geography, 2009, (02):144–148.
5) Guo Xinwei. Research on Credit Risk Measurement for Small and Medium-sized Enterprises in China [D]. Tianjin: Nankai University, 2012.
6) Zhou Chuanxin, Sun Yi, Wang Degang, et al. Review of Federal Learning Research [J]. Journal of Network and Information Security, 2021,7(05):77-92.
7) Bhandary, R., & Ghosh, B. K. Credit Card Default Prediction: An Empirical Analysis on Predictive Performance Using Statistical and Machine Learning Methods[J]. Journal of Risk and Financial Management, 2025, 18(1), 23.
8) Alonso, A., & Carbó, J. M. Understanding the performance of machine learning models to predict credit default: a novel approach for supervisory evaluation[J]. Banco de España Working Paper, 2021, No. 2105.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Deng Ke (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.