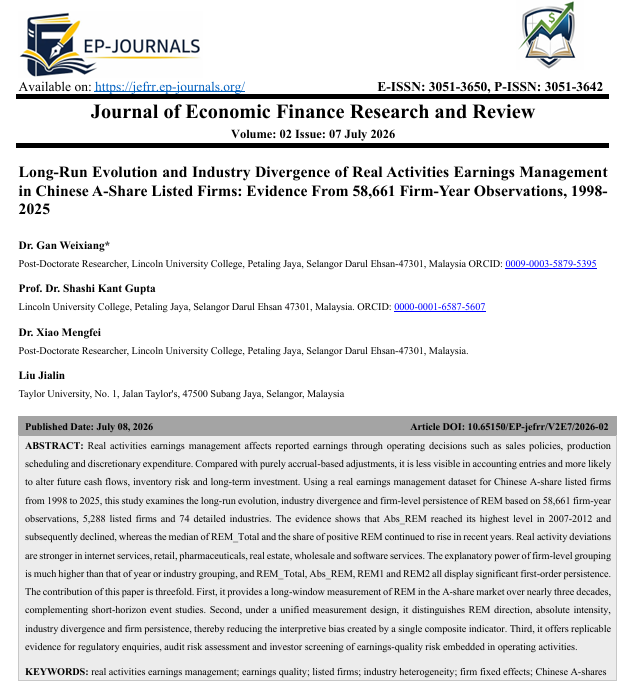
Long-Run Evolution and Industry Divergence of Real Activities Earnings Management in Chinese A-Share Listed Firms: Evidence From 58,661 Firm-Year Observations, 1998-2025
DOI:
https://doi.org/10.65150/EP-jefrr/V2E7/2026-02Keywords:
real activities earnings management, earnings quality, listed firms, industry heterogeneity, firm fixed effects, Chinese A-sharesAbstract
Real activities earnings management affects reported earnings through operating decisions such as sales policies, production scheduling and discretionary expenditure. Compared with purely accrual-based adjustments, it is less visible in accounting entries and more likely to alter future cash flows, inventory risk and long-term investment. Using a real earnings management dataset for Chinese A-share listed firms from 1998 to 2025, this study examines the long-run evolution, industry divergence and firm-level persistence of REM based on 58,661 firm-year observations, 5,288 listed firms and 74 detailed industries. The evidence shows that Abs_REM reached its highest level in 2007-2012 and subsequently declined, whereas the median of REM_Total and the share of positive REM continued to rise in recent years. Real activity deviations are stronger in internet services, retail, pharmaceuticals, real estate, wholesale and software services. The explanatory power of firm-level grouping is much higher than that of year or industry grouping, and REM_Total, Abs_REM, REM1 and REM2 all display significant first-order persistence. The contribution of this paper is threefold. First, it provides a long-window measurement of REM in the A-share market over nearly three decades, complementing short-horizon event studies. Second, under a unified measurement design, it distinguishes REM direction, absolute intensity, industry divergence and firm persistence, thereby reducing the interpretive bias created by a single composite indicator. Third, it offers replicable evidence for regulatory enquiries, audit risk assessment and investor screening of earnings-quality risk embedded in operating activities.
References
1) Schipper, K. (1989). Commentary on earnings management. Accounting Horizons, 3(4), 91-102.
2) Jones, J. J. (1991). Earnings management during import relief investigations. Journal of Accounting Research, 29(2), 193-228. https://doi.org/10.2307/2491047
3) Baber, W. R., Fairfield, P. M., & Haggard, J. A. (1991). The effect of concern about reported income on discretionary spending decisions: The case of research and development. The Accounting Review, 66(4), 818-829.
4) Dechow, P. M., Sloan, R. G., & Sweeney, A. P. (1995). Detecting earnings management. The Accounting Review, 70(2), 193-225.
5) Burgstahler, D., & Dichev, I. (1997). Earnings management to avoid earnings decreases and losses. Journal of Accounting and Economics, 24(1), 99-126. https://doi.org/10.1016/S0165-4101(97)00017-7
6) Bushee, B. J. (1998). The influence of institutional investors on myopic R&D investment behavior. The Accounting Review, 73(3), 305-333.
7) Teoh, S. H., Welch, I., & Wong, T. J. (1998). Earnings management and the long-run market performance of initial public offerings. The Journal of Finance, 53(6), 1935-1974. https://doi.org/10.1111/0022-1082.00079
8) Teoh, S. H., Welch, I., & Wong, T. J. (1998). Earnings management and the underperformance of seasoned equity offerings. Journal of Financial Economics, 50(1), 63-99. https://doi.org/10.1016/S0304-405X(98)00032-4
9) Degeorge, F., Patel, J., & Zeckhauser, R. (1999). Earnings management to exceed thresholds. The Journal of Business, 72(1), 1-33. https://doi.org/10.1086/209601
10) Kasznik, R. (1999). On the association between voluntary disclosure and earnings management. Journal of Accounting Research, 37(1), 57-81. https://doi.org/10.2307/2491396
11) Healy, P. M., & Wahlen, J. M. (1999). A review of the earnings management literature and its implications for standard setting. Accounting Horizons, 13(4), 365-383. https://doi.org/10.2308/acch.1999.13.4.365
12) Dechow, P. M., & Skinner, D. J. (2000). Earnings management: Reconciling the views of accounting academics, practitioners, and regulators. Accounting Horizons, 14(2), 235-250. https://doi.org/10.2308/acch.2000.14.2.235
13) Fields, T. D., Lys, T. Z., & Vincent, L. (2001). Empirical research on accounting choice. Journal of Accounting and Economics, 31(1-3), 255-307. https://doi.org/10.1016/S0165-4101(01)00028-3
14) Francis, J., LaFond, R., Olsson, P. M., & Schipper, K. (2004). Costs of equity and earnings attributes. The Accounting Review, 79(4), 967-1010. https://doi.org/10.2308/accr.2004.79.4.967
15) Francis, J., LaFond, R., Olsson, P., & Schipper, K. (2005). The market pricing of accruals quality. Journal of Accounting and Economics, 39(2), 295-327. https://doi.org/10.1016/j.jacceco.2004.06.003
16) Graham, J. R., Harvey, C. R., & Rajgopal, S. (2005). The economic implications of corporate financial reporting. Journal of Accounting and Economics, 40(1-3), 3-73. https://doi.org/10.1016/j.jacceco.2005.01.002
17) Kothari, S. P., Leone, A. J., & Wasley, C. E. (2005). Performance matched discretionary accrual measures. Journal of Accounting and Economics, 39(1), 163-197. https://doi.org/10.1016/j.jacceco.2004.11.002
18) McVay, S. E. (2006). Earnings management using classification shifting: An examination of core earnings and special items. The Accounting Review, 81(3), 501-531. https://doi.org/10.2308/accr.2006.81.3.501
19) Roychowdhury, S. (2006). Earnings management through real activities manipulation. Journal of Accounting and Economics, 42(3), 335-370. https://doi.org/10.1016/j.jacceco.2006.01.002
20) Cohen, D. A., Dey, A., & Lys, T. Z. (2008). Real and accrual-based earnings management in the pre- and post-Sarbanes-Oxley periods. The Accounting Review, 83(3), 757-787. https://doi.org/10.2308/accr.2008.83.3.757
21) Gunny, K. A. (2010). The relation between earnings management using real activities manipulation and future performance: Evidence from meeting earnings benchmarks. Contemporary Accounting Research, 27(3), 855-888. https://doi.org/10.1111/j.1911-3846.2010.01029.x
22) Dechow, P. M., Ge, W., & Schrand, C. M. (2010). Understanding earnings quality: A review of the proxies, their determinants and their consequences. Journal of Accounting and Economics, 50(2-3), 344-401. https://doi.org/10.1016/j.jacceco.2010.09.001
23) Badertscher, B. A. (2011). Overvaluation and the choice of alternative earnings management mechanisms. The Accounting Review, 86(5), 1491-1518. https://doi.org/10.2308/accr-10092
24) Zang, A. Y. (2012). Evidence on the trade-off between real activities manipulation and accrual-based earnings management. The Accounting Review, 87(2), 675-703. https://doi.org/10.2308/accr-10196
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Dr. Gan Weixiang, Shashi Kant Gupta, Dr. Xiao Mengfei, Liu Jialin (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.