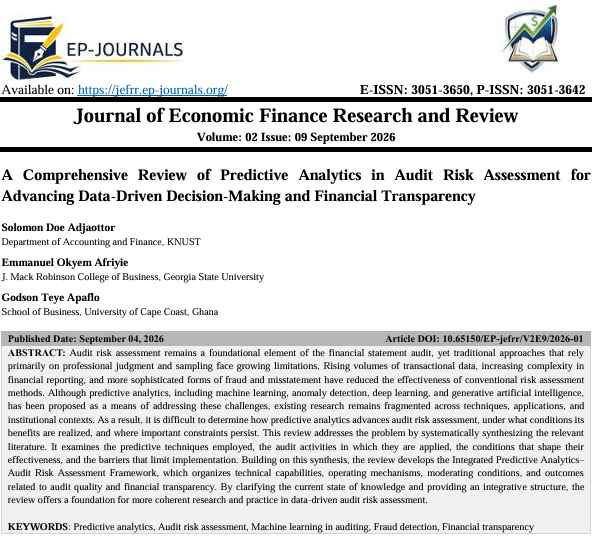
A Comprehensive Review of Predictive Analytics in Audit Risk Assessment for Advancing Data-Driven Decision-Making and Financial Transparency
DOI:
https://doi.org/10.65150/EP-jefrr/V2E9/2026-01Keywords:
Predictive analytics, Audit risk assessment, Machine learning in auditing, Fraud detection, Financial transparencyAbstract
Audit risk assessment remains a foundational element of the financial statement audit, yet traditional approaches that rely primarily on professional judgment and sampling face growing limitations. Rising volumes of transactional data, increasing complexity in financial reporting, and more sophisticated forms of fraud and misstatement have reduced the effectiveness of conventional risk assessment methods. Although predictive analytics, including machine learning, anomaly detection, deep learning, and generative artificial intelligence, has been proposed as a means of addressing these challenges, existing research remains fragmented across techniques, applications, and institutional contexts. As a result, it is difficult to determine how predictive analytics advances audit risk assessment, under what conditions its benefits are realized, and where important constraints persist. This review addresses the problem by systematically synthesizing the relevant literature. It examines the predictive techniques employed, the audit activities in which they are applied, the conditions that shape their effectiveness, and the barriers that limit implementation. Building on this synthesis, the review develops the Integrated Predictive Analytics–Audit Risk Assessment Framework, which organizes technical capabilities, operating mechanisms, moderating conditions, and outcomes related to audit quality and financial transparency. By clarifying the current state of knowledge and providing an integrative structure, the review offers a foundation for more coherent research and practice in data-driven audit risk assessment.
References
1) Akpan, M., & Ogunade, K. M. (2026). Generative artificial intelligence in audit practice: Enhancing risk assessment. Current Issues in Auditing. Advance online publication. https://doi.org/10.2308/CIIA-2025-034
2) Amoako, D., Boboye, C. O., Boateng, V., & Laryea, J. E. N.-L. (2025). Artificial intelligence and machine learning for fraud detection in the U.S. banking industry: Regulatory frameworks, implementation, and challenges. EPRA International Journal of Economics, Business and Management Studies, 12(9). https://doi.org/10.36713/epra23647
3) Ampofo, F. O., Ziorklui, J. E. K., Nyonyoh, N., & Antwi, B. O. (2024). Integrated predictive analytics in IT audit planning. Finance & Accounting Research Journal, 6(7), 1291–1309. https://doi.org/10.51594/farj.v6i7.1324
4) Anwar, A., & Akeel, M. O. (2026). Integrating artificial intelligence in audit workflow: Opportunities, architecture, and challenges: A systematic review. Accounting and Auditing, 2(1), Article 4. https://doi.org/10.3390/accountaudit2010004
5) Ayeomon, O., Amougou, R. S. E., & Ogene, J. O. (2022). Risk-based audit engagement planning: Incorporation of predictive analytics. Communication in Physical Sciences, 8(4), 817–829. https://journalcps.com/index.php/volumes/article/view/808
6) Benyasrisawat, P., & Ounlert, N. (2026). Fraud risk and audit opinions across countries: Complementing accounting-based fraud risk with machine learning methods. Journal of Risk and Financial Management, 19(1), Article 26. https://doi.org/10.3390/jrfm19010026
7) Christensen, B. E., Emett, S. A., Eulerich, M., & Wood, D. A. (2025). Using artificial intelligence for fraud risk assessment: Evidence from novice and experienced auditors. SSRN. https://doi.org/10.2139/ssrn.5173407
8) Duan, H. K., Vasarhelyi, M. A., & Codesso, M. (2025). Integrating process mining and machine learning for advanced internal control evaluation in auditing. Journal of Information Systems, 39(1), 55–75. https://doi.org/10.2308/ISYS-2022-028
9) Duhova, R., Duhov, A., Georgieva, P., & Lazarova, M. (2026). Enhancing enterprise risk management and internal audit practices by applying machine learning models. Risks, 14(5), 107. https://doi.org/10.3390/risks14050107
10) Esmeralda, A. I. P., & Fadhilah, N. H. K. (2026). Fraud detection and machine learning in auditing: A systematic literature review. Educational Studies and Research Journal, 3(1), 37–46. https://doi.org/10.60036/fy6eyn96
11) Eulerich, M., Summers, S. L., & Wood, D. A. (2025). Artificial intelligence, audit risk, and regulatory uncertainty: A refined analytical model of auditor and client decisions under PCAOB scrutiny. SSRN. https://doi.org/10.2139/ssrn.5245259
12) Föhr, T. L., Schreyer, M., Moffitt, K. C., & Marten, K.-U. (2026). Deep learning meets risk-based auditing: A holistic framework for leveraging foundation and task-specific models in audit procedures. International Journal of Accounting Information Systems, 57, Article 100758. https://doi.org/10.1016/j.accinf.2025.100758
13) Gkegkas, M., Kydros, D., & Pazarskis, M. (2025). Using data analytics in financial statement fraud detection and prevention: A systematic review of methods, challenges, and future directions. Journal of Risk and Financial Management, 18(11), Article 598.https://doi.org/10.3390/jrfm18110598
14) Nartey, O. L., Agyei, E., Anim, B., & Yeboah, M. M. (2026). AI and blockchain in forensic auditing: A review of tools for investigating financial crimes in the U.S. International Journal for Multidisciplinary Research, 8(1). https://doi.org/10.36948/ijfmr.2026.v08i01.63239
15) Ogbonna, N., Musa, S., Taoheed, T. O., & Porter, V. (2025a). Integrating predictive analytics into external audit planning for intelligent risk assessment. World Journal of Advanced Research and Reviews, 28(2), 1580–1590. https://doi.org/10.30574/wjarr.2025.28.2.3903
16) Ogbonna, N., Musa, S., T.O., T., & Porter, V. (2025b). Predictive risk assessment models in banking audits: Opportunities and challenges for external auditors. International Journal of Science and Research Archive, 17(2), 962–974.https://doi.org/10.30574/ijsra.2025.17.2.3115
17) Onyekwuluje, T. P., Akoto-Bamfo, D., Tetteh-Kpakpah, C., Panful, B., & Oware, D. (2025). Evaluating the role of cybersecurity audits in protecting the US capital market. World Journal of Advanced Research and Reviews, 25(2), 974–980.https://doi.org/10.30574/wjarr.2025.25.2.0183
18) Robertson, Z., & Smith, J. (2025). Predictive analytics-based audit planning: Using machine learning to forecast high-risk accounting transactions. SSRN. https://doi.org/10.2139/ssrn.5752442
19) Yan, Z. (2024). Audit risk assessment model construction by incorporating deep learning techniques. Applied Mathematics and Nonlinear Sciences, 9(1), 1–17. https://doi.org/10.2478/amns-2024-2138
20) Yeboah, M. M., Agyei, E., Anim, B., Nwinyi, P., & Nartey, O. L. (2026). AI in financial auditing: Addressing U.S. audit failures and strengthening PCAOB/SEC compliance. Sarcouncil Journal of Economics and Business Management, 5(1), 23–32.https://doi.org/10.5281/zenodo.18188728
21) Yuan, T., Zhang, X., & Chen, X. (2025). Machine learning based enterprise financial audit framework and high risk identification. arXiv. https://doi.org/10.48550/arXiv.2507.06266
22) Zhang Parker, C., Jiang, L., Cho, S., & Vasarhelyi, M. A. (2025). Predicting material misstatements using machine learning. The Accounting Review, 100(6), 225–262. https://doi.org/10.2308/TAR-2024-0035
23) Zygoulis, P. N. (2025). AI-powered predictive analytics in risk-based internal auditing: From reactive to proactive risk management. ResearchGate. https://doi.org/10.13140/RG.2.2.14293.49121
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Solomon Doe Adjaottor, Emmanuel Okyem Afriyie, Godson Teye Apaflo (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.