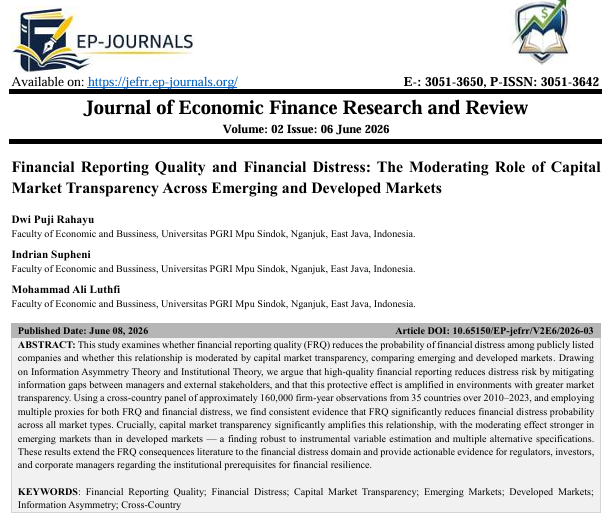
Financial Reporting Quality and Financial Distress: The Moderating Role of Capital Market Transparency Across Emerging and Developed Markets
DOI:
https://doi.org/10.65150/EP-jefrr/V2E6/2026-03Keywords:
Financial Reporting Quality, Financial Distress, Capital Market Transparency, Emerging Markets, Developed Markets, Information Asymmetry, Cross-CountryAbstract
This study examines whether financial reporting quality (FRQ) reduces the probability of financial distress among publicly listed companies and whether this relationship is moderated by capital market transparency, comparing emerging and developed markets. Drawing on Information Asymmetry Theory and Institutional Theory, we argue that high-quality financial reporting reduces distress risk by mitigating information gaps between managers and external stakeholders, and that this protective effect is amplified in environments with greater market transparency. Using a cross-country panel of approximately 160,000 firm-year observations from 35 countries over 2010–2023, and employing multiple proxies for both FRQ and financial distress, we find consistent evidence that FRQ significantly reduces financial distress probability across all market types. Crucially, capital market transparency significantly amplifies this relationship, with the moderating effect stronger in emerging markets than in developed markets — a finding robust to instrumental variable estimation and multiple alternative specifications. These results extend the FRQ consequences literature to the financial distress domain and provide actionable evidence for regulators, investors, and corporate managers regarding the institutional prerequisites for financial resilience.
References
1) Allianz Trade, T. (2025). Global insolvency report March 2025. Allianz Trade Global Research.
2) Altman, E. I. (1968). Financial ratios, discriminant analysis and the prediction of corporate bankruptcy. The Journal of Finance, 23(4), 589–609. https://doi.org/10.1111/j.1540-6261.1968.tb00843.x
3) Ansarada. (2024). Bankruptcy boom: The regions and sectors most affected by financial strain. Ansarada Insights.
4) Asis, G., Bian, C., Bhagat, S., & Zou, H. (2021). In search of distress risk in emerging markets. Journal of International Economics, 131, 103448. https://doi.org/10.1016/j.jinteco.2021.103448
5) Ball, R., Kothari, S. P., & Robin, A. (2000). The effect of international institutional factors on properties of accounting earnings. Journal of Accounting and Economics, 29(1), 1–51. https://doi.org/10.1016/S0165-4101(00)00012-4
6) Beaver, W. H. (1966). Financial ratios as predictors of failure. Journal of Accounting Research, 4(Supplement), 71–111. https://doi.org/10.2307/2490171
7) Biddle, G. C., Hilary, G., & Verdi, R. S. (2009). How does financial reporting quality relate to investment efficiency? Journal of Accounting and Economics, 48(2–3), 112–131. https://doi.org/10.1016/j.jacceco.2009.09.001
8) Bushman, R. M., Piotroski, J. D., & Smith, A. J. (2001). What determines corporate transparency? Journal of Accounting Research, 42(2), 207–252. https://doi.org/10.1111/j.1475-679X.2004.00136.x
9) Bushman, R. M., & Smith, A. J. (2004). Financial accounting information and corporate governance. Journal of Accounting and Economics, 32(1–3), 237–333. https://doi.org/10.1016/S0165-4101(01)00027-1
10) Campbell, J. Y., Hilscher, J., & Szilagyi, J. (2008). In search of distress risk. The Journal of Finance, 63(6), 2899–2939. https://doi.org/10.1111/j.1540-6261.2008.01416.x
11) Dayanandan, A., Donker, H., Ivanof, M., & Karahan, G. (2016). IFRS and accounting quality: Legal origin, regional, and disclosure impacts. International Journal of Accounting and Information Management, 24(3), 296–316. https://doi.org/10.1108/IJAIM-11-2015-0075
12) Dechow, P. M., & Dichev, I. D. (2010). The quality of accruals and earnings: The role of accrual estimation errors. The Accounting Review, 77(Supplement), 35–59. https://doi.org/10.2308/accr.2002.77.s-1.35
13) Ding, W., Levine, R., Lin, C., & Xie, W. (2014). Corporate immunity to the COVID-19 pandemic. Journal of Financial Economics, 141(3), 802–830.
14) Faz, B., Alam, M., & Rahman, M. (2022). Financial distress and earnings quality: Evidence from listed firms. Journal of Contemporary Accounting and Economics, 18(3), 100333.
15) Francis, J., LaFond, R., Olsson, P. M., & Schipper, K. (2004). Costs of equity and earnings attributes. The Accounting Review, 79(4), 967–1010. https://doi.org/10.2308/accr.2004.79.4.967
16) Healy, P. M., & Palepu, K. G. (2001). Information asymmetry, corporate disclosure, and the capital markets: A review of the empirical disclosure literature. Journal of Accounting and Economics, 31(1–3), 405–440. https://doi.org/10.1016/S0165-4101(01)00018-0
17) Jensen, M. C., & Meckling, W. H. (1976). THEORY OF THE FIRM: MANAGERIAL BEHAVIOR, AGENCY COSTS AND OWNERSHIP STRUCTURE. Human Relations, 72(10), 1671–1696. https://doi.org/https://doi.org/10.1177/0018726718812602
18) Khan, M. A., & Safdar, N. (2024). Impact of financial reporting quality on investment efficiency around the globe. Socialis Series in Social Science, 7, 1–16.
19) Kothari, S. P., Leone, A. J., & Wasley, C. E. (2005). Performance matched discretionary accrual measures. Journal of Accounting and Economics, 39(1), 163–197. https://doi.org/10.1016/j.jacceco.2004.11.002
20) La Porta, R., Lopez-de-Silanes, F., Shleifer, A., & Vishny, R. W. (1998). Law and finance. Journal of Political Economy, 106(6), 1113–1155. https://doi.org/10.1086/250042
21) Leuz, C., Nanda, D., & Wysocki, P. D. (2003). Earnings management and investor protection: An international comparison. Journal of Financial Economics, 69(3), 505–527. https://doi.org/10.1016/S0304-405X(03)00121-1
22) McNichols, M. F., & Stubben, S. R. (2008). Does earnings management affect firms’ investment decisions? The Accounting Review, 83(6), 1571–1603. https://doi.org/10.2308/accr.2008.83.6.1571
23) Nurim, Y., Harjanto, N., Elrifi, M. Y., Supheni, I., Wijaya, N. R., & Pribadi, A. (2025). Power distance and gender gap perception on the credit risk of rural banks: Study of social and economic mission of Indonesian rural banks. International Journal of Monetary Economics and Finance, 18(2/3), 165–175.
24) Nuswantara, D. A., Fachruzzaman, S., D., R., Rusdiyanto, R., & Hendrati, I. M. (2023). The role of political connection to moderate board size, woman on boards on financial distress. Cogent Business & Management, 10(1), 2156704.
25) Ohlson, J. A. (1980). Financial ratios and the probabilistic prediction of bankruptcy. Journal of Accounting Research, 18(1), 109–131. https://doi.org/10.2307/2490395
26) Spence, M. (1973). Job Market Signaling. Quarterly Journal of Economics, 87, 355– 374. https://doi.org/10.2307/1882010
27) Suhardjanto, D., Probohudono, A. N., & Supheni, I. (2021). Pengungkapan inovasi disruptif industri perbankan Indonesia’. EKUITAS (Jurnal Ekonomi Dan Keuangan, 5(3), 283–299,. https://doi.org/10.24034/j25485024.y2021.v5.i3.4997
28) Supheni, I., Suhardjanto, D., Rahmawati, & Probohudono, A. N. (2024). Disruptive innovation disclosure practices and application of stakeholder theory. In Macroeconomic Risk and Growth in the Southeast Asian Countries: Insight from SEA (International Symposia in Economic Theory and Econometrics (Vol. 33, pp. 41–51). Emerald Group Publishing. https://doi.org/10.1108/S1571-03862023000033B003
29) Supheni, I., Suyanto, S., & Utami, T. P. (2023). Disruptive innovation disclosure practices: Do board characteristics matter? Accounting and Investment, 25(3), 990–1004.
30) Ulum, I., Murni, S., & Supheni, I. (2024). Pengaruh struktur kepemilikan dan keragaman struktural direksi terhadap inovasi pada perusahaan non keuangan tahun 2017–2021. Jurnal Akuntansi Inovatif, 2(2), 119–128.
31) Zouaghi, F., Garcia-Meca, E., & Martinez Conesa, I. (2024). Navigating firm financial distress in turbulent times: The impact of the institutional context. Business Strategy and the Environment, 33(6), 5312–5327. https://doi.org/10.1002/bse.3917
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Dwi Puji Rahayu, Indrian Supheni, Muhammad Ali Luthfi, SE., M.Si (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.