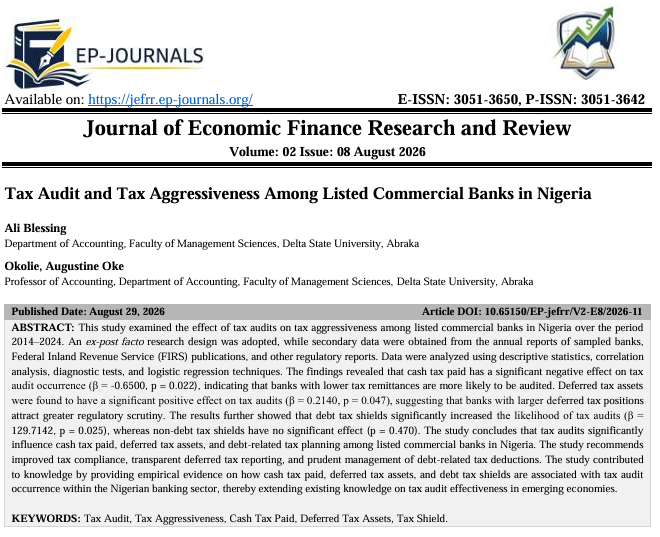
Tax Audit and Tax Aggressiveness Among Listed Commercial Banks in Nigeria
DOI:
https://doi.org/10.65150/EP-jefrr/V2-E8/2026-11Keywords:
Tax Audit, Tax Aggressiveness, Cash Tax Paid, Deferred Tax Assets, Tax Shield.Abstract
This study examined the effect of tax audits on tax aggressiveness among listed commercial banks in Nigeria over the period 2014–2024. An ex-post facto research design was adopted, while secondary data were obtained from the annual reports of sampled banks, Federal Inland Revenue Service (FIRS) publications, and other regulatory reports. Data were analyzed using descriptive statistics, correlation analysis, diagnostic tests, and logistic regression techniques. The findings revealed that cash tax paid has a significant negative effect on tax audit occurrence (β = -0.6500, p = 0.022), indicating that banks with lower tax remittances are more likely to be audited. Deferred tax assets were found to have a significant positive effect on tax audits (β = 0.2140, p = 0.047), suggesting that banks with larger deferred tax positions attract greater regulatory scrutiny. The results further showed that debt tax shields significantly increased the likelihood of tax audits (β = 129.7142, p = 0.025), whereas non-debt tax shields have no significant effect (p = 0.470). The study concludes that tax audits significantly influence cash tax paid, deferred tax assets, and debt-related tax planning among listed commercial banks in Nigeria. The study recommends improved tax compliance, transparent deferred tax reporting, and prudent management of debt-related tax deductions. The study contributed to knowledge by providing empirical evidence on how cash tax paid, deferred tax assets, and debt tax shields are associated with tax audit occurrence within the Nigerian banking sector, thereby extending existing knowledge on tax audit effectiveness in emerging economies.
References
1) Aburajab, L., Maali, B., Jaradat, M., & Alsharairi, M. (2019). Board of directors’ characteristics and tax aggressiveness: Evidence from Jordanian listed firms. Theoretical Economics Letters, 9(1), 2732–2745.
2) Aisyah, P., Adib, N., & Rahmanti, V. N. (2024). Does transfer pricing, sales growth and capital intensity affect tax aggressiveness? Jurnal Reviu Akuntansi dan Keuangan, 14(2), 459–476.
3) Ajube, D., & Jeroh, E. (2023). Determinants of tax aggressiveness among non-financial listed firms in Nigeria. International Journal of Applied Research in Social Sciences, 5(7), 207–220.
4) Akinyemi, B. O., & Ogunleye, F. A. (2021). Tax audit characteristics and tax compliance behaviour in Nigeria. Journal of Taxation and Economic Policy, 8(2), 45–59.
5) Al-Asfour, F., & Saleem, K. A. (2023). Tax ethics and tax compliance: Evidence from emerging markets. Corporate Governance and Organizational Behavior Review, 7(4), 127–136.
6) Alkausar, B., Lasmana, M. S., & Soemarsono, P. N. (2020). Tax aggressiveness: A meta-analysis in agency theory perspective. The International Journal of Applied Business, 4(1), 52.
7) Alqatan, A., Chemingui, S., & Arslan, M. (2024). Effect of audit committee on tax aggressiveness: French evidence. Journal of Risk and Financial Management, 18(1), 5.
8) Amah, C. O., & Nwaiwu, J. N. (2018). Tax audit practice and tax revenue generation in Nigeria. International Journal of Innovative Finance and Economics Research, 6(1), 99–112.
9) Aronmwan, E. J., & Ogbaisi, S. A. (2022). The nexus between standalone risk committees and tax aggressiveness: Evidence from Nigeria. Future Business Journal, 8(9).
10) Arum, E. D. P., Wijaya, R., & Wahyudi, I. (2025). Tax aggressiveness in the energy industry: Insights from emerging countries. International Journal of Accounting and Economics Studies, 12(2), 35–42.
11) Awe, O. I. (2008). The theory and practice of auditing. Gilgal Publications.
12) Chatzi, K., Dedoulis, E., & Leventis, S. (2026). Tax Audit Fees and Corporate Tax Avoidance under a Privatized Tax Enforcement Regime: The case of Greece. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.6905703
13) Chen, S., Chen, X., Cheng, Q., & Shevlin, T. (2010). Are family firms more tax aggressive than non-family firms? Journal of Financial Economics, 95(1), 41–61.
14) Duy, N. V., & Tran, T. Q. (2020). The influence of international standards on SME tax compliance in Vietnam. Finance Research Letters, 40, 101750.
15) Dyreng, S. D., Hanlon, M., & Maydew, E. L. (2008). Long-run corporate tax avoidance. The Accounting Review, 83(1), 61–82.
16) Dyreng, S. D., Hanlon, M., Maydew, E. L., & Thornock, J. R. (2019). Changes in corporate effective tax rates over time. Journal of Financial Economics, 131(3), 663–688.
17) Eze, N. O., & Okoye, E. I. (2020). Tax avoidance and tax aggressiveness in Nigerian deposit money banks. International Journal of Finance and Accounting, 9(2), 45–54.
18) Frank, M. M., Lynch, L. J., & Rego, S. O. (2009). Tax reporting aggressiveness and its relation to aggressive financial reporting. The Accounting Review, 84(2), 467–496.
19) Graham, J. R. (2003). Taxes and corporate finance: A review. Review of Financial Studies, 16(4), 1075–1129.
20) Gyimah, P., Owusu-Afriyie, R., & Appiah, K. O. (2026). Tax audit effectiveness in an emerging market revenue authority: an empirical analysis. IIMT Journal of Management, 1–15. https://doi.org/10.1108/iimtjm-10-2025-0090
21) Hanlon, M., & Heitzman, S. (2010). A review of tax research. Journal of Accounting and Economics, 50(2–3), 127–178.
22) Hanlon, M., & Slemrod, J. (2009). What does tax aggressiveness signal? Evidence from stock price reactions to news about tax shelter involvement. Journal of Public Economics, 93(1–2), 126–141.
23) Ibrahim, M., Musah, A., & Abdul-Hanan, A. (2015). Beyond enforcement: Examining tax compliance from a behavioural perspective. International Journal of Economics, Commerce and Management, 3(5), 1–19.
24) Jayanto, P. Y. (2025). Firm characteristics and tax aggressiveness among property and real estate firms in Indonesia. Journal of Accounting and Taxation Studies, 13(1), 44–58.
25) Kasper, M., & Alm, J. (2022). Audits and post-audit tax compliance. Journal of Economic Behavior & Organization, 195, 87–102.
26) Mahouat, N., Azenzoul, A., Slimane, S. N., Es-Sanoun, M., Mokhlis, K., & Jbene, M. (2025). Corporate Governance and tax aggressiveness: The moderating role of audit quality. Journal of Risk and Financial Management, 19(1), 10. https://doi.org/10.3390/jrfm19010010
27) Ndalu, T. A., Ibanichuka, E. A. L., & Ofurum, C. O. (2021). Deferred tax accounting and earnings quality of listed firms in Nigeria. Nigerian Journal of Accounting Research, 17(2), 85–101.
28) Nuryanah, S., Mahabbatussalma, R., & Satrio, A. (2023). Cash tax payment and tax aggressiveness: Evidence from emerging economies. International Journal of Financial Studies, 11(3), 1–18.
29) Odumade, S. M., & Okolie, A. O. (2025). Tax savings strategies and financial performance of listed consumer goods companies in Nigeria. Global Journal of Economic and Finance Research., 02(12). https://doi.org/10.55677/gjefr/04-2025-vol02e12
30) Ogunbela, A. A., Akinboboye, O. A., & Ogunbiyi, T. A. (2021). Tax audit and tax compliance among corporate taxpayers in Nigeria. Journal of Accounting and Taxation, 13(4), 115–124.
31) Ogundana, O. M., Olayinka, M. U., & Omodero, C. O. (2020). Tax audit practice and corporate tax compliance in Nigeria. Journal of Accounting and Financial Management, 6(3), 87–98.
32) Okoye, E. I., Akenbor, C. O., & Obara, L. C. (2022). Tax audit effectiveness and corporate tax compliance in Nigeria. Journal of Accounting and Taxation, 14(1), 1–10.
33) Omodero, C. O. (2021). Corporate governance and tax compliance: The mediating role of tax audit. Journal of Economics and Sustainable Development, 12(8), 102–109.
34) Onuoha, C. O., & Ezeani, E. J. (2023). Deferred tax and earnings management practices in Nigeria. Journal of Contemporary Accounting, 7(1), 56–70.
35) Osinubi, T. O. (2020). Tax shields and corporate financing decisions in Nigeria. African Journal of Finance and Management, 12(2), 77–91.
36) Phillips, J., Pincus, M., & Rego, S. O. (2003). Earnings management: New evidence based on deferred tax expense. The Accounting Review, 78(2), 491–521.
37) Renouard, C., & Ezvan, C. (2018). Tax planning, tax avoidance and corporate responsibility. Business Ethics Journal Review, 6(1), 1–12.
38) Rixen, T., & Unger, B. (2021). Effective tax enforcement in the digital age. Regulation & Governance, 15(4), 1123–1140.
39) Salihu, I. A., & Kawi, N. S. (2021). Tax planning strategies and corporate tax compliance. International Journal of Economics and Financial Issues, 11(3), 124–132.
40) Sanni, M. R., & Ripiye, O. P. (2024). Board attributes and tax avoidance among listed manufacturing companies in Nigeria. Nigerian Journal of Management Sciences, 25(1), 210–223.
41) Sarra, A., & Lathiifa, N. (2025). Liquidity, leverage, capital intensity and tax aggressiveness: The moderating role of profitability. Journal of Accounting and Finance Research, 14(1), 55–71.
42) Ugwu, C. C., Akubo, J. C., Salifu, A., Ngwoke, M. U., & Audu, S. A. (2024). Board characteristics and tax aggressiveness among listed deposit money banks in Nigeria. International Journal of Accounting and Financial Reporting, 14(2), 95–112.
43) Ugwunta, D. O., Ike, B. N., & Okoli, M. N. (2023). Tax audit and corporate tax compliance among Nigerian banks. African Journal of Accounting and Finance, 15(3), 44–58.
44) Uwejiyan, J., Okolie, A. O. & Ebiaghan, O. F., (2025). Tax compliance cost, tax based broadening and tax revenue in Nigeria. Contemporary Research Analysis Journal., 02(07). https://doi.org/10.55677/craj/06-2025-vol02i07
45) Widiana, R., & Jusuf, A. (2024). Tax audit effectiveness and corporate tax payment behaviour. Journal of Tax Administration, 10(1), 21–37.
46) Wilson, R. J. (2009). An examination of corporate tax shelter participants. The Accounting Review, 84(3), 969–999.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Ali Blessing , Okolie, Augustine Oke (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.