The Associations of Firm Size, Firm Complexity, And Audit Fees with Key Audit Matters Disclosure: The Moderating Role of Auditor Switching
DOI:
https://doi.org/10.65150/EP-jefrr/V2E11/2026-03Keywords:
Key Audit Matters, Firm Size, Firm Complexity, Audit Fees, Auditor Switching.Abstract
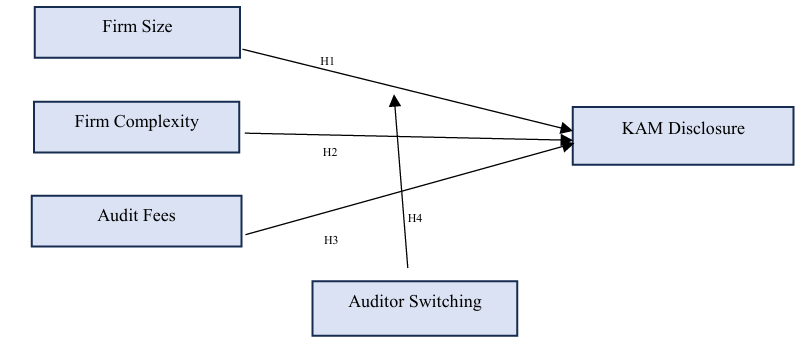
This study examines the association of firm size, firm complexity, and audit fees with the Key Audit Matters (KAM) disclosed in independent auditor’s reports, as well as the moderating role of auditor switching in the relationship between Firm Size and KAM disclosure. The study uses secondary data from industrial sector companies listed on the Indonesia Stock Exchange during 2022–2024. Based on purposive sampling, 46 firms were selected, yielding 138 firm-year observations. KAM disclosure is measured by the number of matters reported in the independent auditor’s report; Firm Size by the natural logarithm of total assets; Firm Complexity by the number of subsidiaries; Audit Fees by the natural logarithm of audit fees; and Auditor Switching by a binary indicator. The data are analyzed using multiple linear regression and moderated regression analysis. The results indicate that Firm Size is positively and significantly associated with KAM disclosure (B = 0.083, p = 0.024). Firm Complexity also exhibits a positive and significant association with KAM disclosure (B = 0.069, p = 0.014), whereas Audit Fees have a negative and significant association (B = −0.102, p = 0.034). Furthermore, the interaction between Firm Size and Auditor Switching is positive and significant (B = 0.998, p = 0.001), suggesting that auditor switching strengthens the positive association between Firm Size and KAM disclosure.
References
1) Alduneibat, K. A. (2024). Factors affecting the level of Key Audit Matters disclosure: Evidence from Jordan. Jordan Journal of Business Administration, 20(2). https://doi.org/10.35516/jjba.v20i2.2008
2) Amin, K. I. Al, & Handayani, R. R. S. (2025). The role of auditor characteristics in Key Audit Matters disclosures: Evidence from Indonesian listed manufacturing companies. Jurnal Dinamika Akuntansi dan Bisnis, 12(1), 133–152. https://doi.org/10.24815/jdab.v12i1.45155
3) Azis, R., Hartanto, R., & Maemunah, M. (2025). The effect of audit fees, audit rotation, and company size on Key Audit Matters disclosure. Bandung Conference Series: Accountancy, 5(1), 469–478. https://doi.org/10.29313/bcsa.v5i1.17233
4) Bepari, M. K., Mollik, A. T., Nahar, S., & Islam, M. N. (2022). Determinants of accounts level and entity level Key Audit Matters: Further evidence. Accounting in Europe, 19(3), 397–422. https://doi.org/10.1080/17449480.2022.2060753
5) de Ricquebourg, A. D., & Maroun, W. (2023). How do auditor rotations affect Key Audit Matters? Archival evidence from South African audits. The British Accounting Review, 55(2), 101099. https://doi.org/10.1016/j.bar.2022.101099
6) Dinata, I., & Cheisviyanny, C. (2024). The influence of an overlapped audit committee on Key Audit Matters disclosure in Indonesia. Journal of Accounting Exploration, 6(4), 1433–1448
7) Dusadeedumkoeng, O., Gandía, J. L., & Huguet, D. (2023). Determinants of key audit matters in Thailand. Journal of Competitiveness, 15(3), 184–206. https://doi.org/10.7441/joc.2023.03.10
8) Elmarzouky, M., Hussainey, K., & Abdelfattah, T. (2023). The key audit matters and the audit cost: Does governance matter? International Journal of Accounting & Information Management, 31(1), 195–217. https://doi.org/10.1108/IJAIM-08-2022-0178
9) Ferizqi, L., & Reskino, R. (2024). Determinants of Key Audit Matters disclosure in Indonesia: Evidence from the Kompas100 index. CURRENT: Journal of Current Accounting and Business Studies, 5(2), 325–337. https://doi.org/10.31258/current.5.2.325-337
10) Ferreira, C., & Morais, A. I. (2020). Analysis of the relationship between company characteristics and Key Audit Matters disclosed. Revista Contabilidade & Finanças, 31(83), 262–274. https://doi.org/10.1590/1808-057x201909040
11) Financial Services Authority. (2023). Financial Services Authority Regulation Number 30 of 2023 concerning the Communication of Key Audit Matters in Public Accountants’ Reports on Audited Financial Statements in the Capital Market.
12) Hay, D. C., Knechel, W. R., & Wong, N. (2006). Audit fees: A meta-analysis of the effect of supply and demand attributes. Contemporary Accounting Research, 23(1), 141–191. https://doi.org/10.1506/4XR4-KT5V-E8CN-91GX
13) International Auditing and Assurance Standards Board. (2015). International Standard on Auditing 701: Communicating Key Audit Matters in the independent auditor’s report.
14) Indonesian Institute of Certified Public Accountants. (2021). Audit Standard 701 (2021): Communicating Key Audit Matters in the Independent Auditor's Report.
15) Jensen, M. C., & Meckling, W. H. (1976). Theory of the firm: Managerial behavior, agency costs and ownership structure. Journal of Financial Economics, 3(4), 305–360.
16) Kirana, G. C., & Indriansyah, M. R. (2022). The influence of company size, audit opinion, audit firm size, and audit tenure on auditor switching. Jurnal Liabilitas, 7(1), 44–54. https://doi.org/10.54964/liabilitas.v7i1.194
17) Lin, H.-L., & Yen, A.-R. (2022). Auditor rotation, Key Audit Matter disclosures, and financial reporting quality. Advances in Accounting, 57, 100594. https://doi.org/10.1016/j.adiac.2022.100594
18) Mah, O. A., & Mardini, G. H. (2022). Matters may matter: The disclosure of Key Audit Matters in the Middle East. Cogent Economics & Finance, 10(1). https://doi.org/10.1080/23322039.2022.2111787
19) Nasser, A. T. A., Wahid, E. A., Nazri, S. N. F. S. M., & Hudaib, M. (2006). Auditor-client relationship: The case of audit tenure and auditor switching in Malaysia. Managerial Auditing Journal, 21(7), 724–737. https://doi.org/10.1108/02686900610680512
20) Özcan, A. (2021). Kilit denetim konularının açıklanmasını hangi faktörler etkiler? İmalat firmalarından kanıtlar. International Journal of Management Economics and Business, 17(1), 149–161. https://doi.org/10.17130/ijmeb.796444
21) Pinto, I., & Morais, A. I. (2019). What matters in disclosures of Key Audit Matters: Evidence from Europe. Journal of International Financial Management & Accounting, 30(2), 145–162. https://doi.org/10.1111/jifm.12095
22) Pratama, Y. M., & Lusiani, H. (2024). The influence of Key Audit Matter disclosure, firm size, and profitability on audit report lag. Transekonomika: Accounting, Business, and Finance, 4(5), 869–879.
23) Puryati, D., Septiana, D. P., & Tifani, D. I. (2025). The effect of company complexity and auditor size on audit fee: A study on financial sector on the Indonesia Stock Exchange (IDX) (2021–2023). Journal of Management and Muamalah, 15(2), 20–33. https://doi.org/10.53840/jmm.v15i2.284
24) Putra, R. J. P., & Dwita, S. (2024). The influence of company characteristics on Key Audit Matters (KAM). Wahana Riset Akuntansi, 12(1), 79. https://doi.org/10.24036/wra.v12i1.124626
25) Rahman, M. H., Musyaffi, A. M., & Nindito, M. (2024). The influence of profitability, corporate risk, and firm size on audit fees. Journal of Accounting, Taxation, and Auditing, 5(1), 954–965. https://doi.org/10.21009/japa.0501.06
26) Rhamadhani, N. G., & Heriyati, D. (2025). The impact of company financial performance and audit fees on the disclosure of Key Audit Matters (KAM). Jurnal Akuntansi dan Keuangan, 27(1), 35–49.
27) Robiah, R. H., & Sudrajat, S. (2025). Determination of Key Audit Matters for financial sector companies listed on the Indonesia Stock Exchange in 2022 and 2023. Journal of Business Economics and Accounting, 5(1), 16–27. https://doi.org/10.55606/jebaku.v5i1.4998
28) Sania, W., & Ali, S. (2024). The impact of audit fee, size of public accounting firm, company size, and leverage on the communication of Key Audit Matters. Eduvest - Journal of Universal Studies, 4(10), 9547–9564. https://doi.org/10.59188/eduvest.v4i10.38822
29) Sierra-García, L., Gambetta, N., García-Benau, M. A., & Orta-Pérez, M. (2019). Understanding the determinants of the magnitude of entity-level risk and account-level risk key audit matters: The case of the United Kingdom. The British Accounting Review, 51(3), 227–240. https://doi.org/10.1016/j.bar.2019.02.004 IDEAS/RePEc
30) Simunic, D. A. (1980). The pricing of audit services: Theory and evidence. Journal of Accounting Research, 18(1), 161–190. https://doi.org/10.2307/2490397
31) Spence, M. (1973). Job market signaling. The Quarterly Journal of Economics, 87(3), 355–374.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Zahwatul Nabila Panjaitan, Andreas Tan, Supriono (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.