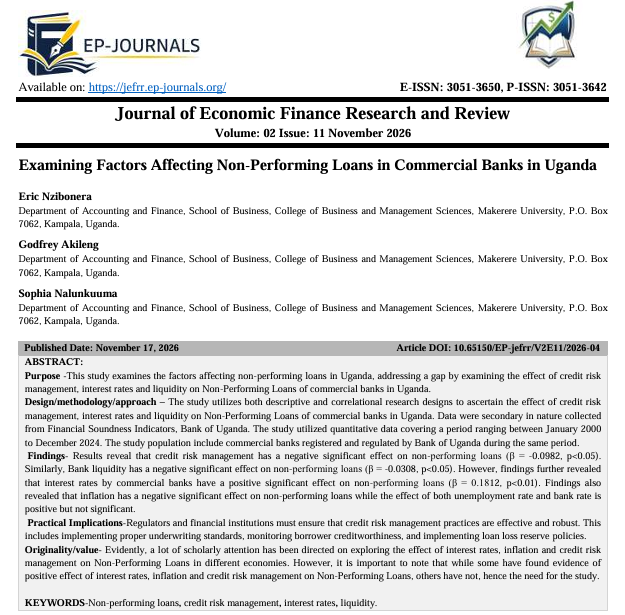
Examining Factors Affecting Non-Performing Loans in Commercial Banks in Uganda
DOI:
https://doi.org/10.65150/EP-jefrr/V2E11/2026-04Keywords:
Non-performing loans, credit risk management, interest rates, liquidityAbstract
Purpose -This study examines the factors affecting non-performing loans in Uganda, addressing a gap by examining the effect of credit risk management, interest rates and liquidity on Non-Performing Loans of commercial banks in Uganda.
Design/methodology/approach – The study utilizes both descriptive and correlational research designs to ascertain the effect of credit risk management, interest rates and liquidity on Non-Performing Loans of commercial banks in Uganda. Data were secondary in nature collected from Financial Soundness Indicators, Bank of Uganda. The study utilized quantitative data covering a period ranging between January 2000 to December 2024. The study population include commercial banks registered and regulated by Bank of Uganda during the same period.
Findings- Results reveal that credit risk management has a negative significant effect on non-performing loans (β = -0.0982, p<0.05). Similarly, Bank liquidity has a negative significant effect on non-performing loans (β = -0.0308, p<0.05). However, findings further revealed that interest rates by commercial banks have a positive significant effect on non-performing loans (β = 0.1812, p<0.01). Findings also revealed that inflation has a negative significant effect on non-performing loans while the effect of both unemployment rate and bank rate is positive but not significant.
Practical Implications-Regulators and financial institutions must ensure that credit risk management practices are effective and robust. This includes implementing proper underwriting standards, monitoring borrower creditworthiness, and implementing loan loss reserve policies.
Originality/value- Evidently, a lot of scholarly attention has been directed on exploring the effect of interest rates, inflation and credit risk management on Non-Performing Loans in different economies. However, it is important to note that while some have found evidence of positive effect of interest rates, inflation and credit risk management on Non-Performing Loans, others have not, hence the need for the study.
References
1) Abaidoo, R. (2018). Loan delinquency and macroeconomic conditions: An ARDL and error correction approach. American Journal of Business, 33(3), 82–95. https://doi.org/10.1108/AJB-03-2018-0006
2) Abrar, A. (2019). The impact of financial and social performance of microfinance institutions on lending interest rate: Cross-country evidence. Cogent Business & Management, 6(1), 1540072. https://doi.org/10.1080/23311975.2018.1540072
3) Absanto, G., & Aikaruwa, D. (2013). Credit rationing and loan repayment performance: The case study of Victoria Savings and Credit Cooperative Society. Global Advanced Research Journal of Management and Business Studies, 2(6).
4) Adams, K. A., & McGuire, E. K. (2023). Research methods, statistics, and application (3rd ed.). SAGE.
5) Adelina, G., Saranda, T., & Bajrami, R. (2022). The impact of Macro-Economic Factors on Non-Performing Loans in the Western Balkans. Emerging Science Journal, 6(5): 1032- 1045.
6) Agaba, F., Tamwesigire, C., & Eton, M. (2022). Credit risk management practices and loan performance of commercial banks in Uganda. Business Perspective Review, 4(1), 16–28. https://doi.org/10.38157/bpr.v4i1.394
7) Bank of Uganda. (2019). Bank of Uganda annual supervision report. Bank of Uganda.
8) Bank of Uganda. (2021a). Bank of Uganda annual report.
9) Bank of Uganda. (2021b). Financial soundness indicators. https://www.bou.or.ug/bou/bouwebsite/Statistics/
10) Byrne, B. M. (2010). Structural equation modeling with AMOS: Basic concepts, applications, and programming. Taylor & Francis Group.
11) Ekinci, R., & Poyraz, G. (2019). The effect of credit risk on financial performance of deposit banks in Turkey. Procedia Computer Science, 158, 979–987. https://doi.org/10.1016/j.procs.2019.09.139
12) Emekter, R., Tu, Y., Jirasakuldech, B., & Lu, M. (2015). Evaluating credit risk and loan performance. [Publication details incomplete].
13) Ghosh, R., Sen, K. K., & Riva, F. (2020). Behavioral determinants of nonperforming loans in Bangladesh. Asian Journal of Accounting Research, 5(2), 327–340. https://doi.org/10.1108/AJAR-03-2020-0018.
14) Hair, J. F., Black, W. C., Babin, B. J., & Anderson, R. E. (2010). Multivariate data analysis: A global perspective. Prentice Hall.
15) Hosseini, S. S., Khaledi, M., Ghorbani, M., & Brewin, D. G. (2012). An analysis of transaction costs of obtaining credits in rural Iran. Journal of Agricultural Science and Technology, 14, 243–256.
16) Jacques, K., & Nigro, P. (1997). Risk-based capital, portfolio risk, and bank capital: A simultaneous equations approach. Journal of Economics and Business, 49(6), 533–547. https://doi.org/10.1016/S0148-6195(97)00038-6.
17) Kline, R. B. (2011). Methodology in the social sciences: Principles and practice of structural equation modeling. Guilford Press.
18) Kothari, C. R. (2004). Research methodology: Methods and techniques. New Age International Publishers.
19) Lawrence, B., Sarpong, P., & Doorasamy, M. (2020). The impact of credit risk on performance: A case of South African commercial banks. Global Business Review, 1–14.
20) Lihawa, J. P., & Ngaruko, D. D. (2021). Impact of non-performing loans on credit growth in the banking industry in Tanzania: 2009–2018. Asian Journal of Economics, Business and Accounting, 10–18. https://doi.org/10.9734/ajeba/2021/v21i330357.
21) Long, V. M., Yen, N. T., & Long, P. D. (2020). Factors affecting non-performing loans (NPLs) of banks: The case of Vietnam. HCMCOUJS—Economics and Business Administration, 10(2). https://doi.org/10.46223/HCMCOUJS.econ.en.10.2.967.2020
22) Louzis, D. P., Vouldis, A. T., & Metaxas, V. L. (2012). Macroeconomic and bank-specific determinants of non-performing loans in Greece: A comparative study of mortgage, business and consumer loan portfolios. Journal of Banking & Finance, 36(4), 1012–1027. https://doi.org/10.1016/j.jbankfin.2011.10.012
23) Mdaghri, A. A. (2022). How does bank liquidity affect non-performing loans in MENA region? International Journal of Emerging Markets, 17(7), 1635–1658.
24) Mulyungi, W., & Mulyungi, M. (2020). Effect of client appraisal on financial performance of financial institutions in Rwanda: A case study of Guaranty Trust Bank Rwanda PLC. International Journal of Science and Research, 9(6).
25) Nikolaidou, E., & Vogiazas, S. D. (2014). Credit risk determinants for the Bulgarian banking system. International Advances in Economic Research, 20(1), 87–102. https://doi.org/10.1007/s11294-013-9444-x
26) Ninson, A., Sidza, A., & Ampah, D. (2021). The nexus among non-performing loans, lending rates and financial performance of banks in Ghana. International Journal of Finance and Banking Research, 7(5), 123. https://doi.org/10.11648/j.ijfbr.20210705.13
27) Ntiamoah, E. B., Egyiri, P. O., Fiaklou, D., & Kwamega, M. (2014). An assessment of credit management practices on loan performance.
28) Obae, G., & Jagongo, A. (2022). Credit management practices and loan performance of commercial banks in Kenya. International Academic Journal of Economics and Finance, 3(7).
29) Ofori-Abebrese, G., Pickson, R. B., & Opare, E. (2016). The effect of bank-specific factors on loan performance of HFC Bank in Ghana. International Journal of Economics and Finance, 8(7), 185. https://doi.org/10.5539/ijef.v8n7p185.
30) Ogundipe, A. S., Akintola, A. F., & Olaoye, S. A. (2020). Interest rates and loan performance of deposit money banks in Nigeria. EPRA International Journal of Economic and Business Review, A13–A20. https://doi.org/10.36713/epra3014.
31) Olabamiji, O., & Michael, O. (2018). Credit management practices and bank performance: Evidence from First Bank. South Asian Journal of Social Studies and Economics, 1–10. https://doi.org/10.9734/sajsse/2018/v1i125772
32) Olanike, B., & Abass, J. A. (2014). Prime lending rates and the performance of microfinance banks in Nigeria. European Journal of Business and Management, 7.
33) Pham, N. H., & Tan, N. N. (2021). Applying Bayesian method to investigate determinants of non-performing loans of banks in Vietnam. Science & Technology Development Journal—Economics—Law and Management, 5(1).
https://doi.org/10.32508/stdjelm.v5i1.704.
34) Pop, I. D., Cepoi, C. O., & Anghel, D. G. (2018). Liquidity-threshold effect in non-performing loans. Finance Research Letters, 27, 124–128. https://doi.org/10.1016/j.frl.2018.02.012
35) Qaisi, F. A. (2020). The influence of interest rates on size of the credit facilities and deposits in commercial banks of Jordan (1990–
2018).
36) Rahbar, F., & Behzadi Soufiani, M. (2021). The impact of macroeconomic and banking variables on non-performing loans in oil cycles: Evidence from Iran. Journal of Money and Economy, 16(2), 135–164. https://doi.org/10.52547/jme.16.2.135
37) Ross, S. A., Westerfield, R. W., & Jordan, B. D. (2020). Essentials of corporate finance (10th ed.). McGraw-Hill Education.
38) Salifu, T. A., Tofik-Abu, Z., Rahman, A. M., & Mohammed, S. A. (2018). Determinants of loan repayment performance of small and medium enterprises (SMEs) in Ghana: The case of Asante Akyem Rural Bank. Journal of African Business,
39) Sangwan, A. S., Wan Rasheed, M., & Bakar, A. S. (2022). Effect of interest rate on loan repayment in microfinance banks in Malaysia. Journal of Finance and Accounting, 6(3), 1–10. https://doi.org/10.53819/81018102t5081
40) Serwadda, I. (2018). Impact of credit risk management systems on the financial performance of commercial banks in Uganda. Acta Universitatis Agriculturae et Silviculturae Mendelianae Brunensis, 66(6), 1627–1635. https://doi.org/10.11118/actaun201866061627.
41) Sharifi, S., Haldar, A., & Rao, S. V. D. N. (2019). The relationship between credit risk management and non-performing assets of commercial banks in India. Managerial Finance, 45(3), 399–412. https://doi.org/10.1108/MF-06-2018-0259
42) Siddiqui, M. A. (2018). Interest rates impact on loan repayment performance of MSMEs. Jaipuria International Journal of Management Research, 4(2), 76–81.
43) Sivarajan, L. S., Alyasa-Gan, S. S., Che-Yahya, N., & Salehuddin, S. (2023). Explaining non-performing loans of commercial banks in Malaysia. Advances in Social Sciences Research Journal, 10(6.2), 98–106.
44) Suleyman, D. (2022). Comparison of normality tests in terms of sample sizes under different skewness and kurtosis coefficients. International Journal of Assessment Tools in Education, 9(2), 397–409.
45) Sunday, S., Sawandi, N., & Mohamad, A. A.-H. (2019). Working capital management and firm performance: The moderating effect of inflation rates. Social Sciences and Humanities, 27(1), 235–257.
46) Szarowska, I. (2018). Effect of macroeconomic determinants on non-performing loans in Central and Eastern European countries. International Journal of Monetary Economics and Finance, 11(1), 20–35.
47) Tanui, J., Wanyoike, D., & Ngahu, S. (2015). Assessment of credit risk management practices on financial performance among deposit taking SACCOs in Nakuru East Sub County, Kenya. International Journal in Management and Social Science, 3(5), 602–610.
48) Tham, K.-W., Said, R., & Mohd Adnan, Y. (2022). Dynamic implications of GDP, interest rates, taxes, income, foreign direct investments, housing prices on property NPLs. International Journal of Housing Markets and Analysis, 15(5), 1122–1144. https://doi.org/10.1108/IJHMA-07-2021-0078.
49) Theophilus, B. (2021). Liquidity of mortgage collaterals and non-performing loans effects in Nigerian deposit money banks. International Journal of Advances in Engineering and Management, 3, 12.
50) Washington, G. K. (2014). Effects of macroeconomic variables on credit risk in the Kenyan banking system. International Journal of Business and Commerce, 3(9), 1–26.
51) Zhongming, T., Mpeqa, R., Mensah, I. A., Ding, G., & Musah, M. (2019). On the nexus of credit risk management and bank performance: A dynamic panel testimony from some selected commercial banks in China. Journal of Financial Risk Management, 8(2), 125–145. https://doi.org/10.4236/jfrm.2019.82009.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Eric Nzibonera, Godfrey Akileng, Sophia Nalunkuuma (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.