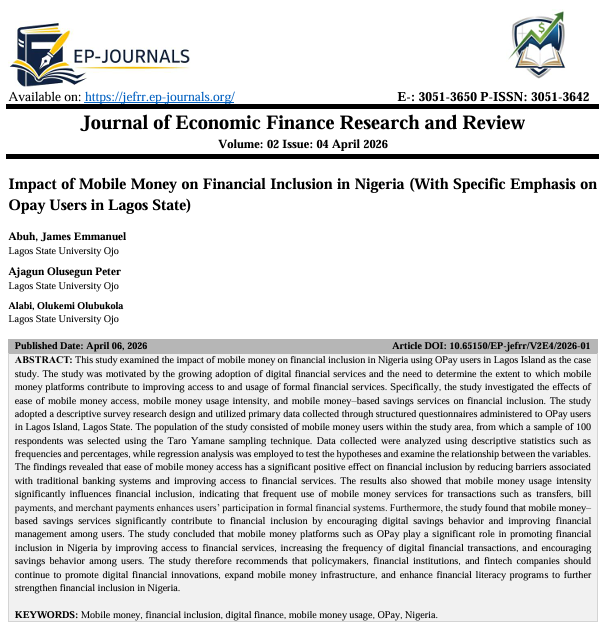
Impact of Mobile Money on Financial Inclusion in Nigeria (With Specific Emphasis on Opay Users in Lagos State)
DOI:
https://doi.org/10.65150/EP-jefrr/V2E4/2026-01Keywords:
Mobile money, financial inclusion, digital finance, mobile money usage, OPay, Nigeria.Abstract
This study examined the impact of mobile money on financial inclusion in Nigeria using OPay users in Lagos Island as the case study. The study was motivated by the growing adoption of digital financial services and the need to determine the extent to which mobile money platforms contribute to improving access to and usage of formal financial services. Specifically, the study investigated the effects of ease of mobile money access, mobile money usage intensity, and mobile money–based savings services on financial inclusion. The study adopted a descriptive survey research design and utilized primary data collected through structured questionnaires administered to OPay users in Lagos Island, Lagos State. The population of the study consisted of mobile money users within the study area, from which a sample of 100 respondents was selected using the Taro Yamane sampling technique. Data collected were analyzed using descriptive statistics such as frequencies and percentages, while regression analysis was employed to test the hypotheses and examine the relationship between the variables. The findings revealed that ease of mobile money access has a significant positive effect on financial inclusion by reducing barriers associated with traditional banking systems and improving access to financial services. The results also showed that mobile money usage intensity significantly influences financial inclusion, indicating that frequent use of mobile money services for transactions such as transfers, bill payments, and merchant payments enhances users’ participation in formal financial systems. Furthermore, the study found that mobile money–based savings services significantly contribute to financial inclusion by encouraging digital savings behavior and improving financial management among users. The study concluded that mobile money platforms such as OPay play a significant role in promoting financial inclusion in Nigeria by improving access to financial services, increasing the frequency of digital financial transactions, and encouraging savings behavior among users. The study therefore recommends that policymakers, financial institutions, and fintech companies should continue to promote digital financial innovations, expand mobile money infrastructure, and enhance financial literacy programs to further strengthen financial inclusion in Nigeria.
References
1) Adeyemi, A. A., & Lawal, O. A. (2023). Fintech innovation and financial inclusion in Nigeria: Evidence from mobile money operators. Journal of African Business, 24(4), 512–529.
2) Ajagun, O. P., Awogbayila, S. O., Adeniran, O. S. (2025). Forensic Accounting as a Tool for Fraud Detection and Prevention in Nigeria (A Survey of Chosen Public Corporations in Nigeria). International Journal Of Research And Innovation In Applied Science (Ijrias), ISSN No. 2454-6194 | DOI: 10.51584/IJRIAS |Volume X Issue VII.
3) Akinwale, Y. O., & Kyari, A. K. (2022). Mobile money adoption and financial inclusion in Nigeria. Journal of African Business, 23(4), 589–605.
4) Allen, F., Demirgüç-Kunt, A., Klapper, L., & Martinez Peria, M. S. (2022). The foundations of financial inclusion: Understanding ownership and use of formal accounts. Journal of Financial Intermediation, 50, 100912.
5) Central Bank of Nigeria. (2023). Financial inclusion newsletter. Central Bank of Nigeria.
6) Demirgüç-Kunt, A., Klapper, L., Singer, D., & Ansar, S. (2021). The Global Findex Database 2021: Financial inclusion, digital payments, and resilience in the age of COVID-19. World Bank.
7) Demirgüç-Kunt, A., Klapper, L., Singer, D., & Ansar, S. (2022). The Global Findex Database 2021: Financial inclusion, digital payments, and resilience in the age of COVID-19. World Bank.
8) Demirgüç-Kunt, A., Martinez Peria, M. S., & Tressel, T. (2023). The global expansion of digital financial services and financial inclusion. World Bank Research Observer, 38(2), 205–229.
9) Enhancing Financial Innovation & Access (EFInA). (2023). Access to financial services in Nigeria survey 2023. EFInA.
10) GSMA. (2023). State of the industry report on mobile money 2023. GSMA.
11) Nairametrics. (2025). Mobile money operators process over ₦71 trillion transactions in 2024. Nairametrics.
12) Ozili, P. K. (2023). Financial inclusion research around the world: A review. Forum for Social Economics, 52(2), 165–189.
13) Ozili, P. K. (2024). Digital finance, regulation, and financial inclusion in Africa. African Development Review, 36(1), 1–15.
14) Suri, T., & Jack, W. (2022). The long-run poverty and gender impacts of mobile money. Science, 354(6317), 1288–1292.
15) Venkatesh, V., & Bala, H. (2008). Technology acceptance model 3 and a research agenda on interventions. Decision Sciences, 39(2), 273–315.
16) Venkatesh, V., Thong, J. Y. L., & Xu, X. (2012). Consumer acceptance and use of information technology: Extending the unified theory of acceptance and use of technology. MIS Quarterly, 36(1), 157–178.
17) World Bank. (2022). Financial inclusion and inclusive growth. World Bank Group.
18) World Bank. (2024). Digital financial services and inclusive development in Sub-Saharan Africa. World Bank Group.
19) World Bank. (2025). Global economic prospects: Digital finance and development. World Bank Group.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Abuh, James Emmanuel, Ajagun Olusegun Peter, Alabi, Olukemi Olubukola (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.