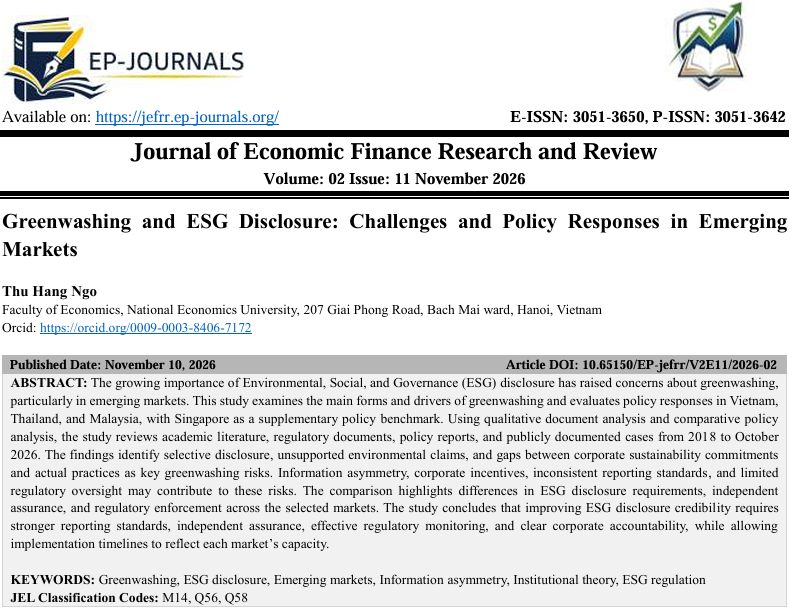
Greenwashing and ESG Disclosure: Challenges and Policy Responses in Emerging Markets
DOI:
https://doi.org/10.65150/EP-jefrr/V2E11/2026-02Keywords:
ESG disclosure, Emerging Markets, green washing, Information Asymmetry, Institutional theory, ESG regulationAbstract
The growing importance of Environmental, Social, and Governance (ESG) disclosure has raised concerns about greenwashing, particularly in emerging markets. This study examines the main forms and drivers of greenwashing and evaluates policy responses in Vietnam, Thailand, and Malaysia, with Singapore as a supplementary policy benchmark. Using qualitative document analysis and comparative policy analysis, the study reviews academic literature, regulatory documents, policy reports, and publicly documented cases from 2018 to October 2026. The findings identify selective disclosure, unsupported environmental claims, and gaps between corporate sustainability commitments and actual practices as key greenwashing risks. Information asymmetry, corporate incentives, inconsistent reporting standards, and limited regulatory oversight may contribute to these risks. The comparison highlights differences in ESG disclosure requirements, independent assurance, and regulatory enforcement across the selected markets. The study concludes that improving ESG disclosure credibility requires stronger reporting standards, independent assurance, effective regulatory monitoring, and clear corporate accountability, while allowing implementation timelines to reflect each market’s capacity.
References
1) Accounting and Corporate Regulatory Authority. (2026, July 27). Sustainability Reporting and Assurance Requirements. Accounting and Corporate Regulatory Authority. https://www.acra.gov.sg/regulations/sustainability-reporting/requirements-timeline/
2) Akerlof, G. A. (1970). The Market for “Lemons”: Quality Uncertainty and the Market Mechanism. The Quarterly Journal of Economics, 84(3), 488. https://doi.org/10.2307/1879431
3) Bank Negara Malaysia. (2021). Climate Change and Principle-based Taxonomy. https://www.bnm.gov.my/-/climate-change-principle-based-taxonomy
4) Bowen, G. A. (2009). Document Analysis as a Qualitative Research Method. Qualitative Research Journal, 9(2), 27–40.https://doi.org/10.3316/QRJ0902027
5) Braun, V., & Clarke, V. (2006). Using thematic analysis in psychology. Qualitative Research in Psychology, 3(2), 77–101.https://doi.org/10.1191/1478088706qp063oa
6) Bursa Malaysia Securities Berhad. (n.d.). Sustainability Reporting Guide. Retrieved October 12, 2026, from
7) Christmann, P., & Taylor, G. (2006). Firm self-regulation through international certifiable standards: determinants of symbolic versus substantive implementation. Journal of International Business Studies, 37(6), 863–878. https://doi.org/10.1057/palgrave.jibs.8400231
8) Circular No. 96/2020/TT-BTC: Guiding the Disclosure of Information on the Securities Market. (2020). https://chinhphu.vn/default.aspx?docid=201902&pageid=27160
9) Jamali, D., & Karam, C. (2018). Corporate Social Responsibility in Developing Countries as an Emerging Field of Study. International Journal of Management Reviews, 20(1), 32–61. https://doi.org/10.1111/ijmr.12112
10) Marano, V., Tashman, P., & Kostova, T. (2017). Escaping the iron cage: Liabilities of origin and CSR reporting of emerging market multinational enterprises. Journal of International Business Studies, 48(3), 386–408. https://doi.org/10.1057/jibs.2016.17
11) Meyer, J. W., & Rowan, B. (1977). Institutionalized Organizations: Formal Structure as Myth and Ceremony. American Journal of Sociology, 83(2), 340–363. https://doi.org/10.1086/226550
12) Ministry of Finance of Vietnam. (2026). Consolidated Document No. 10/VBHN-BTC on Information Disclosure in the Securities Market. https://ssc.gov.vn/webcenter/portal/ubck/pages_r/l/chitit?dDocName=APPSSCGOVVN1620166110
13) Monetary Authority of Singapore. (n.d.). Taxonomy. Monetary Authority of Singapore. Retrieved October 10, 2026, from https://www.mas.gov.sg/development/sustainable-finance/taxonomy
14) Oliver, C. (1991). STRATEGIC RESPONSES TO INSTITUTIONAL PROCESSES. Academy of Management Review, 16(1), 145–179.https://doi.org/10.5465/amr.1991.4279002
15) Prime Minister of Vietnam. (2025). Decision No. 21/2025/QD-TTg on Environmental Criteria and the Confirmation of Investment Projects Classified under the Green Taxonomy. https://chinhphu.vn/?classid=0&docid=214447&pageid=27160
16) Securities and Exchange Commission, T. (2020). Annual Registration Statement and Annual Report, Form 56-1 One Report. https://www.sec.or.th/TH/pages/lawandregulations/financialstatementsandreportsundersection56.aspx.
17) Securities and Exchange Commission, T. (2025, November 28). SEC revises sustainability related disclosure principles to align with ISSB standards. https://www.sec.or.th/TH/Pages/News_Detail.aspx?SECID=12309
18) Securities Commission Malaysia. (2024). National Sustainability Reporting Framework.https://www.sc.com.my/api/documentms/download.ashx?id=e98c3900-7b35-4cf5-a07d-fd17acf8734e&utm
19) Securities Commission Malaysia. (2026, September 17). ACSR’s Mandatory Sustainability Assurance Requirement to Take Effect in 2028. Securities Commission Malaysia. https://www.sc.com.my/resources/media/media-release/acsrs-mandatory-sustainability-assurance-requirement-to-take-effect-in-2028
20) Spence, M. (1973). Job Market Signaling. The Quarterly Journal of Economics, 87(3), 355. https://doi.org/10.2307/1882010
21) Tashman, P., Marano, V., & Kostova, T. (2019). Walking the walk or talking the talk? Corporate social responsibility decoupling in emerging market multinationals. Journal of International Business Studies, 50(2), 153–171. https://doi.org/10.1057/s41267-018-0171-7
22) Thailand Taxonomy Board. (2025). Thailand Taxonomy Phase 2. https://www.thaibma.or.th/EN/BondInfo/ESG.aspx
23) Yu, E. P., Luu, B. Van, & Chen, C. H. (2020a). Greenwashing in environmental, social and governance disclosures. Research in International Business and Finance, 52, 101192. https://doi.org/10.1016/j.ribaf.2020.101192
24) Yu, E. P., Luu, B. Van, & Chen, C. H. (2020b). Greenwashing in environmental, social and governance disclosures. Research in International Business and Finance, 52, 101192. https://doi.org/10.1016/j.ribaf.2020.101192
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Thu Hang Ngo (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.